



In JPMorgan crypto news, the bank, alongside Chase, Citigroup, Bank of America and Wells Fargo, confirmed plans to create a shared tokenized custodial network through The Clearing House, the real-time payments company they collectively own, with a target launch in the first half of 2027.
The network, running on blockchain infrastructure, will enable 24/7 instant settlement and programmable payments while keeping every dollar in the regulated banking system. It is the largest coordinated banking movement toward blockchain technology in U.S. history and a direct response to stablecoin issuers like Tether and Circle.
Here is the central tension this article uncovers: Bank-grade tokenized deposits and crypto-native stablecoins are now racing toward the same finish line, instantaneous and programmable digital dollars, but they are built on fundamentally different foundations, serve different users, and carry different risks.
This news comes as Bitcoin remains stable on the day, just above $63,300, while the total crypto market cap fell 2.9% in the last 24 hours, now reaching $2.22 trillion, up from $2.7 trillion just 10 days ago.
$BTC fell again to $61,000.
The sellers are in complete control and are trying to push Bitcoin below $60,000.
Once that happens, we will see total capitulation. pic.twitter.com/JWsFi9qOqJ
– Ted (@TedPillows) June 5, 2026
Tokenized Deposits Explained: What the Regulated Settlement Network Really Does and Why Banks Want It
A tokenized deposit is like a digital locker ticket for your bank balance. You exchange your dollars for a blockchain-based token representing that amount, which can be transferred instantly to anyone on the network at any time. Once cashed out, the recipient gets real bank dollars, no separate crypto wallet or assets needed.
What it is not: a new cryptocurrency, a private stablecoin, or a central bank digital currency (CBDC). It remains within the banking system, maintaining the same credit protection and accounting treatment as the funds in your checking account.
The regulated settlement network connects bank payment rails to this blockchain, allowing member banks to instantly transfer tokenized deposits, a process known as atomic settlement. Citi’s token services already facilitate real-time transfers between major cities, serving as a model for scaling this network.
Key benefits include 24/7 settlement, programmable payments via smart contracts, and instant finality rather than waiting for clearing the next business day.
DISCOVER: Best new cryptocurrencies to invest in in 2026
JPMorgan Crypto News: What Jamie Dimon and Citi’s Blockchain Bet Really Signals for the Financial System
JUST IN: JPMorgan, Citi and major US banks to launch new tokenized deposit system to compete with crypto.
– Watcher.Guru (@WatcherGuru) June 4, 2026
JPMorgan’s Kinexys platform has processed institutional payments using JPM Coin on a private blockchain since 2020. In 2026, JPMorgan launched a tokenized deposit token on Base, Coinbase’s public layer 2 network, indicating its willingness to adopt public blockchain technology. The move shows that JPMorgan views blockchain interoperability as an asset rather than a threat.
Citi’s Shahmir Khaliq pointed out that banks aren’t just experimenting with blockchain; they react to stable companies that take on payment and settlement activities. David Watson, CEO of The Clearing House, described the initiative as a significant industry shift towards on-chain payments.
Not all banks share the same urgency. Bank of America’s Mark Monaco noted a lack of immediate demand for tokenized deposits, but acknowledged that adoption takes time. The planned launch in 2027 reflects a proactive approach to building infrastructure ahead of demand.
EXCLUSIVE: Earn $10 USDC via Binance Signup
Will Tokenized Deposits Replace Stablecoins? What RSN Means for USDT and USDC
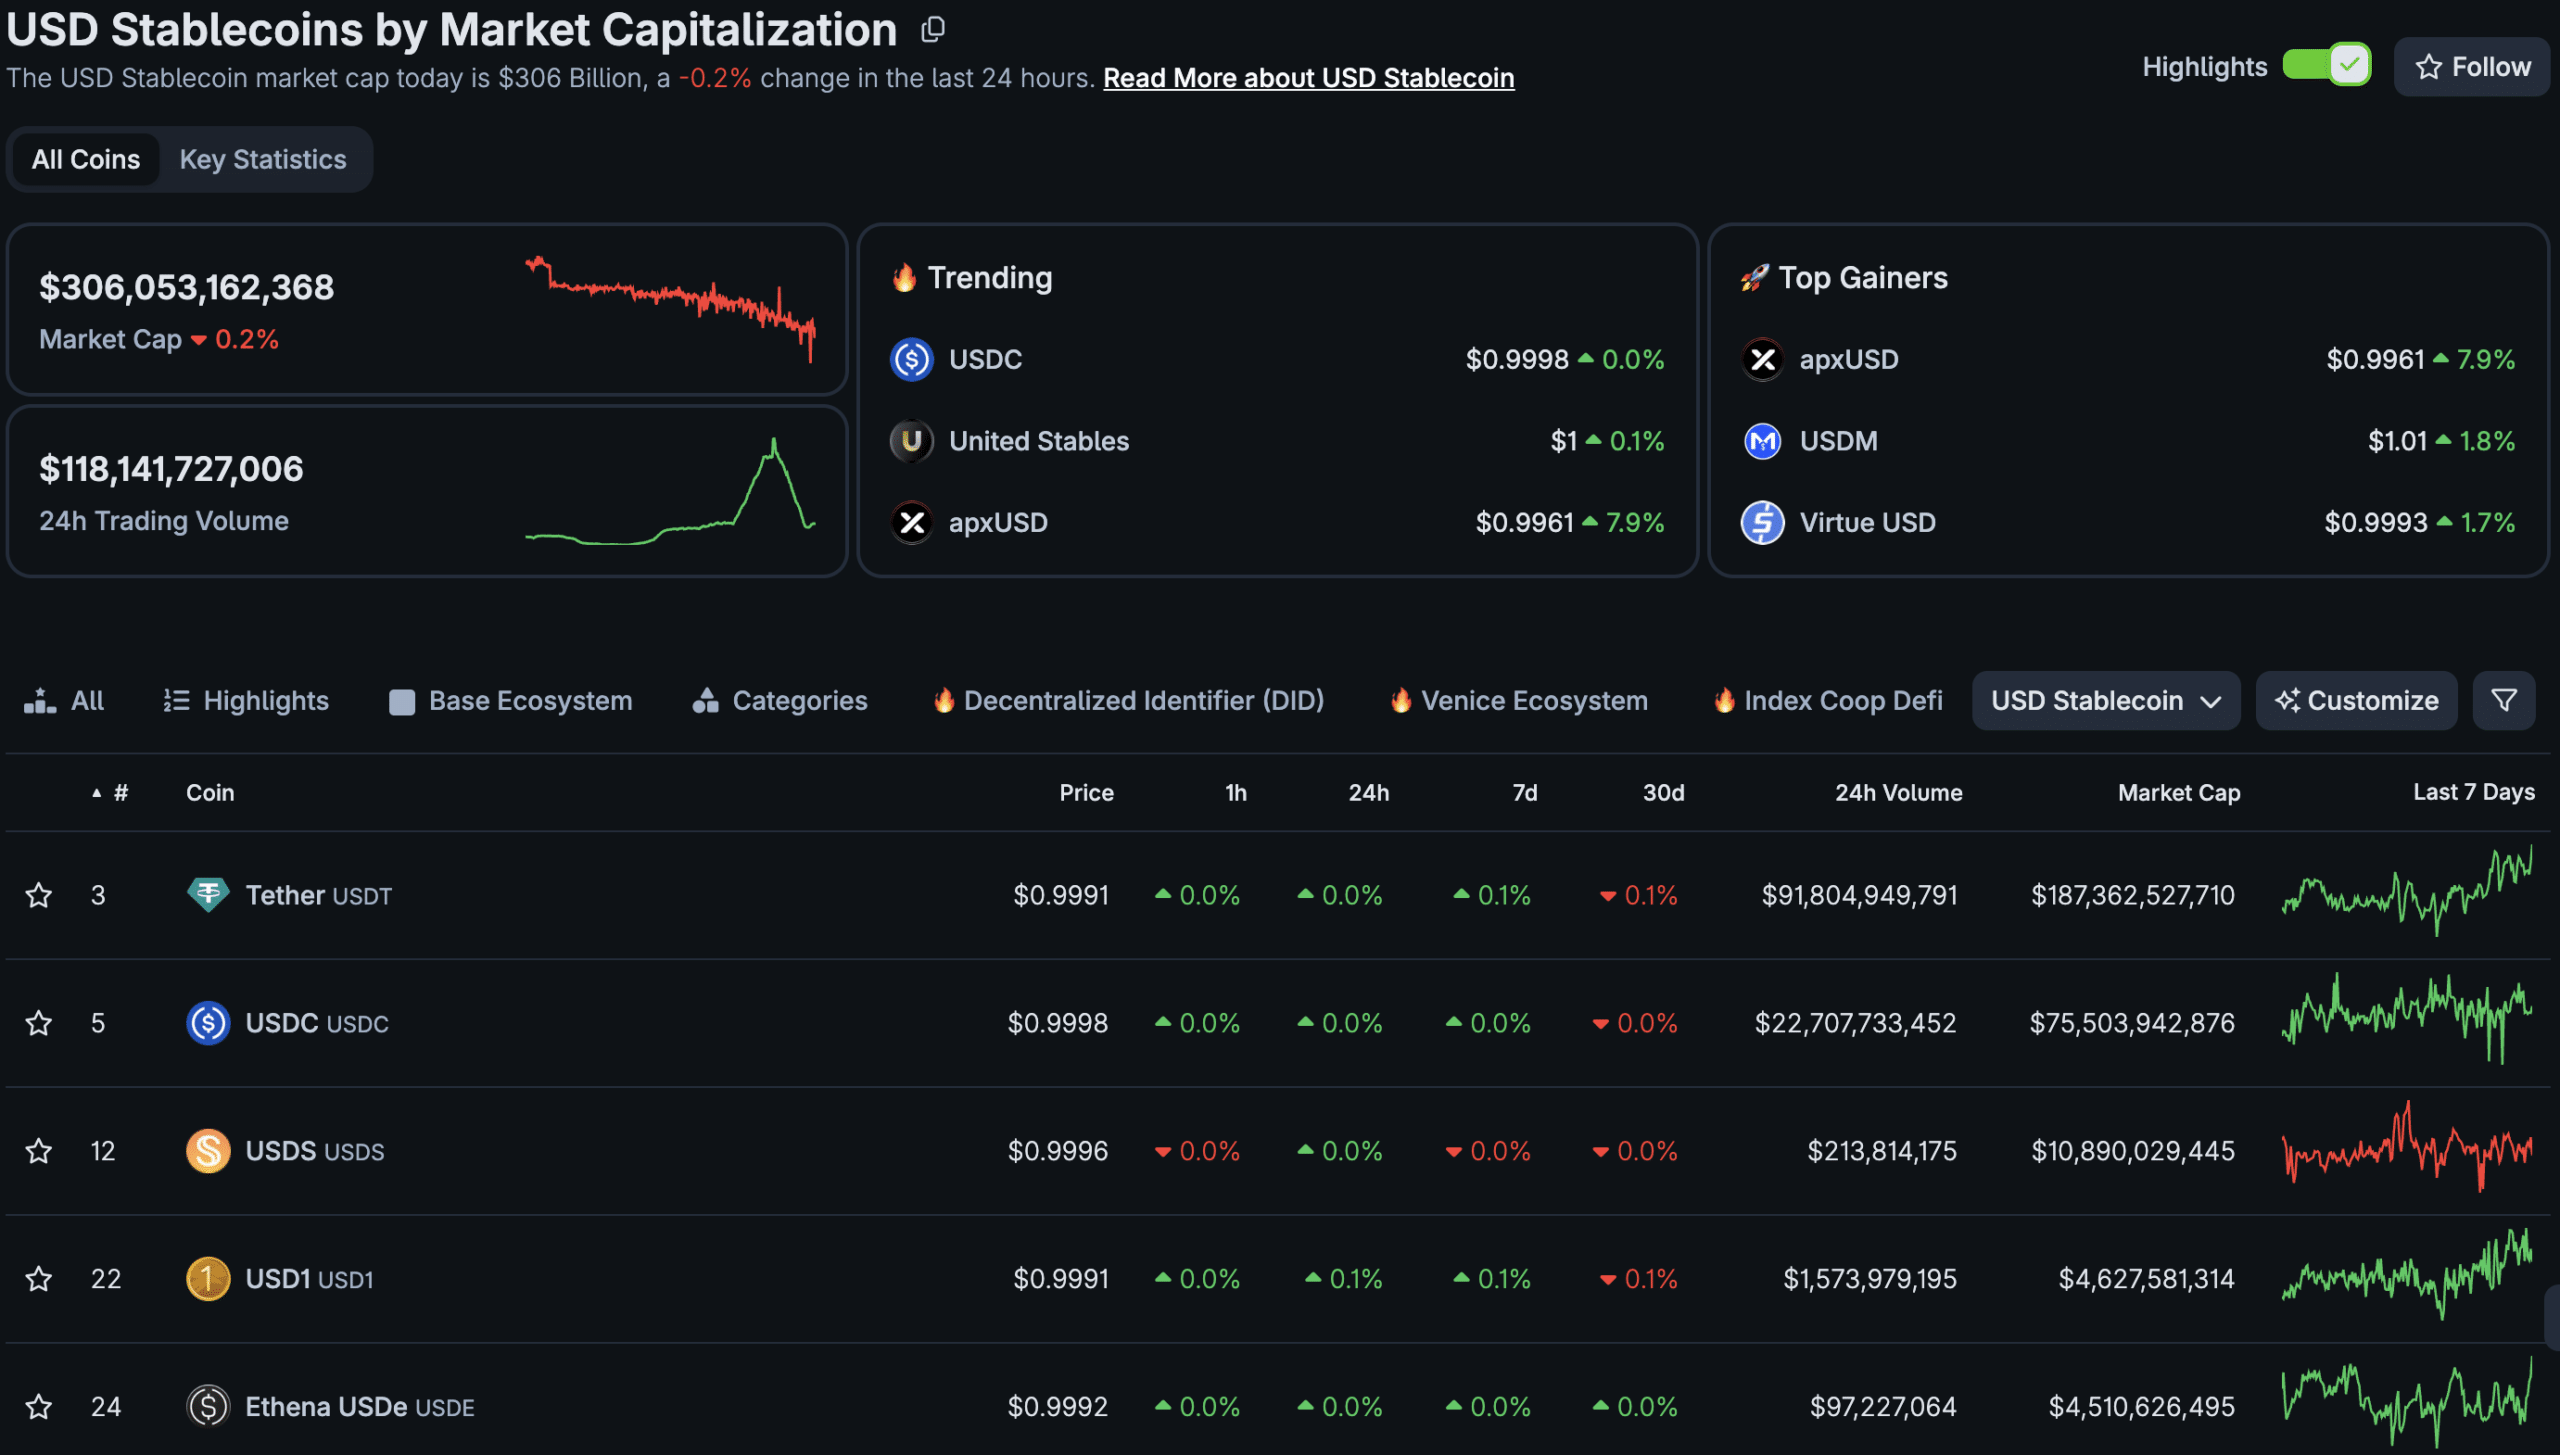
(SOURCE: CoinGecko)
The honest answer is that tokenized repositories attract some users but not others. They excel at wholesale institutional settlement, making them an ideal choice for corporate treasurers handling large transactions, especially with their instant settlement and FDIC-equivalent protections. For example, the JPMorgan crypto digital bank depository could be an attractive alternative to holding USDC.
However, tokenized deposits face challenges in the retail sector, where stablecoins like USDT and USDC thrive. These stablecoins are aimed at people without bank accounts in the United States and those in high-inflation economies who seek exposure to the dollar, benefiting from their permissionless access.
Stablecoin issuers do not remain inactive; companies like Circle and Tether are working to obtain regulatory approvals to enter the institutional market. The landscape is evolving with bank-backed stablecoin initiatives like SoFi USD and Ripple’s RLUSD targeting the same segment of the regulated dollar.
Case of the bull: Tokenized deposits and stablecoins coexist, banks dominate institutional settlement, and stablecoins thrive in DeFi and emerging markets.
Reference case: By 2029, tokenized deposits will likely lead institutional interbank settlements, while USDT and USDC maintain their dominance in retail trading.
Bear case: Stricter regulations on stablecoins could accelerate their decline in regulated markets, limiting their institutional reach faster than companies can adapt.
EXPLORE: Best Meme Coin ICOs to invest in 2026
The article JPMorgan Crypto Revolution: Will Tokenized Deposits Kill Stablecoins? appeared first on 99Bitcoins.


